Check out this article to discover the most common personal and practice-level barriers, and get tips to leverage a more structured approach to help physical therapy practice owners move their whole financial life forward with more confidence.
Why do physical therapy practice owners delay financial planning? The short answer to that big question:
Physical therapy practice owners often delay financial planning because urgent operational demands consume their attention, business often feels like it’s going fine, so deeper planning gets pushed off, and their business and personal finances are deeply connected, making the planning process feel unapproachable. Many also lack a clear financial baseline, feel unsure where to begin, or assume a future practice sale will make up for gaps in personal wealth building.
The delay is understandable. But it is also worth addressing now. The sooner a plan is put in place, the sooner financial goals are achieved. Delaying the conversation doesn’t change the outcomes; it just delays reaching goals.
Financial planning for healthcare practice owners is not limited to choosing investments or calculating a retirement date. It includes understanding how the practice supports the owner, how money moves between the business and household, and whether today’s decisions are building the future the owner actually wants.
Key Takeaways
- The urgent demands of patient care, staffing, billing, and healthcare practice management frequently push long-term planning aside.
- Practice owners often wait for stable cash flow, more revenue, or more time—even though planning can help create that stability and clarity.
- A physical therapy practice owner’s business and personal finances should be kept distinct for accounting purposes, but considered together when setting long-term goals.
- Uncertainty about owner compensation, taxes, retirement savings, debt, and practice value can turn planning into an overwhelming project.
- Structured guidance makes financial planning more manageable by establishing a baseline, prioritizing the next decisions, and creating a regular review process.
Why Is Financial Planning Different for a Physical Therapy Practice Owner?
A salaried employee can often build a financial plan around a relatively predictable paycheck, employer benefits, and personal savings. A physical therapy practice owner has more moving parts. Practice owners assume more risk, but also generate more opportunities for reward.
Patient volume, payer mix, reimbursement timing, payroll, rent, equipment, marketing, and expansion decisions all affect what the practice can produce. The owner must then decide how much to reinvest, how to compensate themselves, how much liquidity to retain, and how to build wealth outside the business.
That is why physical therapy business finance and personal planning cannot be treated as unrelated conversations. A choice that appears sensible for the practice may work against the owner’s household goals, and vice versa.
Why Do PT Practice Owners Put Financial Planning Off?
Most financial planning challenges for physical therapy owners fall into three categories: limited time, incomplete financial visibility, and the complexity of connecting practice decisions to household goals.
1. Urgent practice demands crowd out important planning
There is always something that needs attention now: a staffing issue, an insurance denial, a full treatment schedule, a lease decision, or equipment that needs to be replaced.
Financial planning rarely arrives with the same urgency. Because the consequences of delay are not always immediate, it becomes easy to move the work to next month or next quarter.
This is not a lack of discipline. It is a bandwidth problem. Owners who spend their days moving between clinician, manager, and CEO responsibilities may have very little decision-making energy left for long-term financial strategy.
2. They are waiting for the practice to feel more stable, or in some cases…unstable?
Many owners tell themselves they will start planning when revenue is more predictable, debt is lower, the next therapist is hired, or the new location is profitable. Or, conversely, practice feels stable and comfortable. The owner feels successful, not maybe not as successful as they could. Success has stagnated, but there’ not sure what to do next.
The finish line keeps moving.
Planning does not require perfect stability or uncomfortable urgency. In fact, a useful plan should account for variable revenue, uneven collections, unexpected expenses, and changing business priorities. The goal is not to predict every month perfectly; it is to decide how the owner will respond when reality differs from the forecast.
3. Practice and household finances feel like two different worlds
Owners may have a bookkeeper monitoring the practice, a CPA preparing tax returns, and a financial advisor managing investments. Yet no one may be looking at how the pieces affect one another.
That fragmentation creates questions such as:
- Am I paying myself appropriately?
- How much should remain in the business?
- Can the practice support both expansion and personal savings goals?
- How should debt repayment compete with retirement funding?
- What would happen to my household if I could not work?
When every decision seems connected to five others, postponing all of them can feel safer than making the wrong move.
4. The numbers are available, but they are not decision-ready
Practice owners may receive income statements, balance sheets, production reports, and bank statements without knowing which figures deserve their attention.
The American Physical Therapy Association notes that financial reporting can become burdensome and less useful when it is difficult to interpret or overwhelming. Simplified reporting can help owners focus on a smaller set of meaningful metrics and review them consistently.
Without a clear baseline, financial planning becomes abstract. Owners may know the clinic is busy without knowing whether it is producing enough profit, liquidity, and owner benefit to support their long-term goals.
5. They keep putting the practice first
Reinvesting in the business can be necessary and productive. Problems arise when the owner habitually funds every business need before their own compensation, reserves, debt reduction, or retirement goals.
Over time, the practice may become larger while the owner’s personal balance sheet remains underdeveloped. The owner has built a valuable job or business, but not necessarily a diversified financial life.
The right balance will vary by practice stage. What matters is that the tradeoff is intentional rather than automatic.
6. They assume the sales of the practice will fund retirement
For many owners, the practice may be one of their largest assets. It is tempting to view a future sale as a retirement plan.
But a practice’s eventual value, timing, marketability, taxes, transaction terms, and the owner’s readiness to step away are not guaranteed. If the business depends heavily on the owner’s clinical production or relationships, its value to a buyer may also differ from what the owner expects.
Early planning does not force an owner to sell. It creates options by helping them understand what the practice may contribute to retirement, and what still needs to be built outside it.
7. Financial planning feels personal, complex, or uncomfortable
Financial decisions can bring up fear, embarrassment, disagreement between spouses, or concern that an advisor will judge past choices.
Owners may also believe they need more money before professional financial planning is worthwhile. In reality, some of the most valuable early work involves clarifying cash flow, owner compensation, debt priorities, protection needs, and the purpose of the practice.
You do not need to have everything organized before starting. Getting organized can be part of the process.
What Can Delayed Financial Planning Affect?
The cost of waiting is not a single dramatic event. More often, it is a series of missed opportunities to coordinate decisions.
Delay may affect an owner’s ability to:
- Build an appropriate cash reserve for the practice and household
- Plan proactively for estimated taxes and avoid preventable surprises
- Evaluate owner compensation in the context of business and personal goals
- Choose and maintain a retirement plan that fits the practice and its eligible employees
- Coordinate debt repayment, investing, insurance, and family priorities
- Understand how practice value fits into retirement or succession planning
- Prepare the business to operate with less dependence on the owner
Tax and retirement-plan decisions are especially dependent on entity structure, household income, employee eligibility, and current law. There is no universal percentage or plan type that is right for every PT owner. Those decisions should be made with qualified professionals who understand the owner’s full situation.
How Does Structured Guidance Help Owners Start Sooner?
The solution to complexity is not a longer list of disconnected tasks. It is a step-by-step sequence.
Start with a baseline
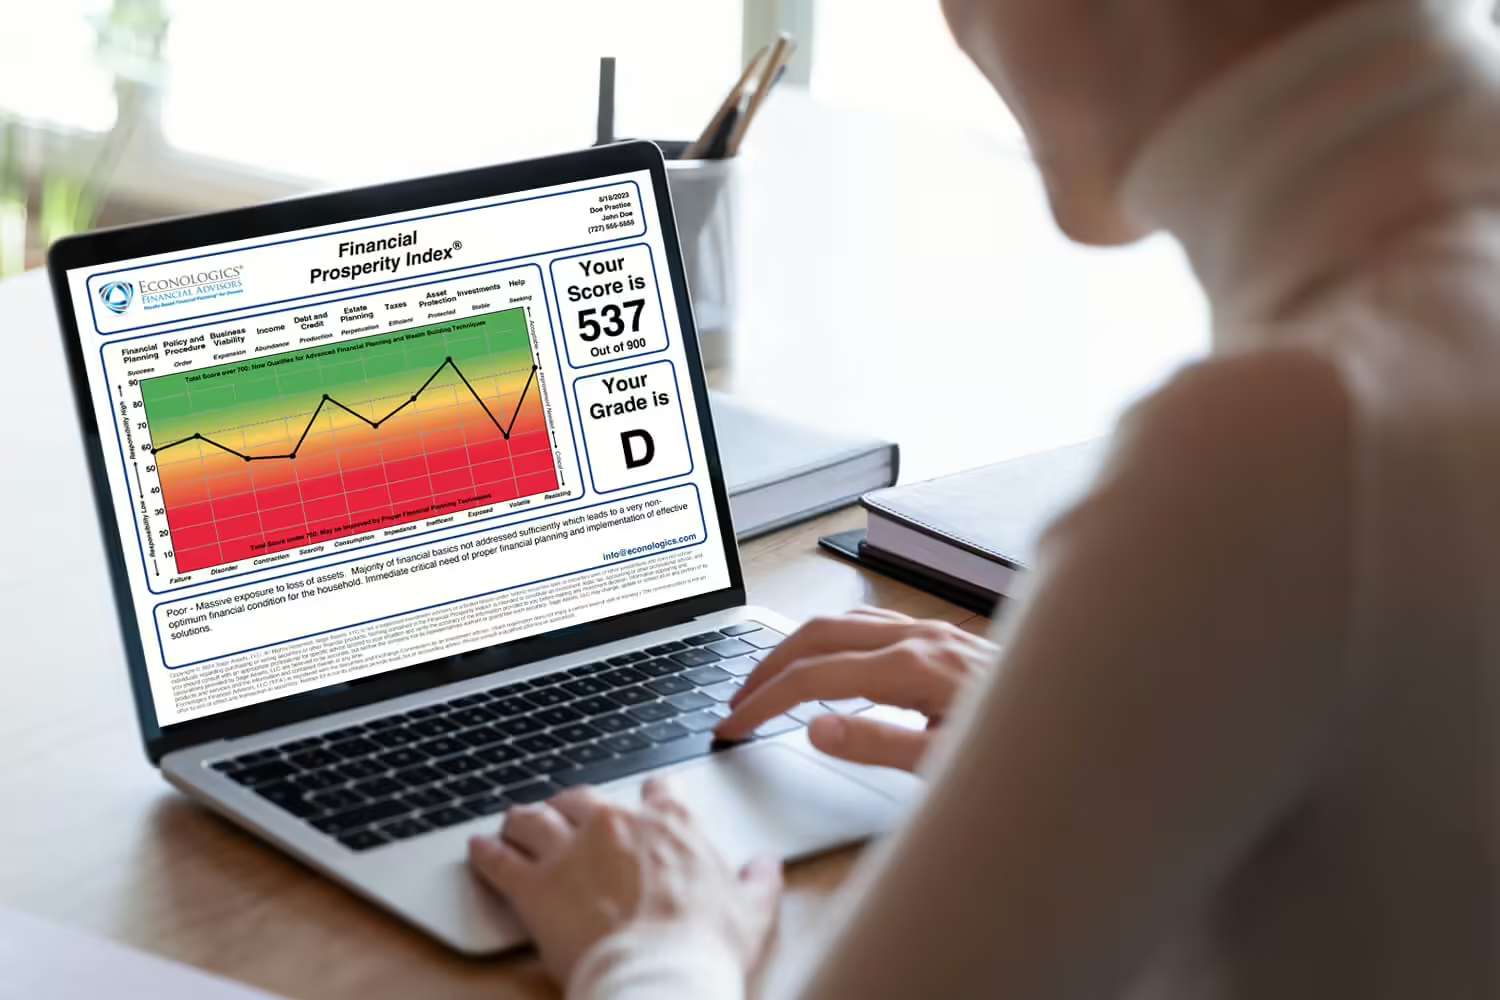
Before recommending strategies, establish where the owner and practice stand today. That may include practice profitability, owner compensation, cash reserves, debts, personal savings, insurance coverage, retirement progress, and an initial assessment of the practice’s value.
Connect the practice to the owner’s goals
The practice is a financial engine, not the final destination. Planning should connect business decisions to the life the owner wants the business to support, whether that means more family time, financial independence, expansion, a future sale, or the freedom to reduce clinical hours.
Prioritize the next few decisions
Trying to fix everything at once creates more paralysis. A structured plan identifies what matters now, what can wait, and which decisions depend on earlier work.
Coordinate the professionals involved
Financial advisors, CPAs, attorneys, valuation professionals, and medical business consulting specialists may each play a role. Their work is most useful when it supports a shared set of goals rather than producing separate recommendations in isolation.
Review the plan regularly
A plan should change as the practice changes. Regular reviews can help an owner compare actual results with expectations, address new risks, and adjust priorities after hiring, expansion, tax changes, family events, or a shift in the owner’s exit timeline.
What Is the Best First Step for a PT Practice Owner?
Start by answering five questions:
- How much does the practice need each month to operate comfortably?
- How much is the owner receiving from the practice, and is that supporting household goals?
- What financial obligations or risks create the most stress today?
- What is the owner building outside the practice?
- What should the practice make possible within the next three, five, and ten years?
You do not need perfect answers. The gaps reveal where planning should begin.
Financial Planning Should Support the Life Behind the Practice
Physical therapy practice owners do not delay financial planning because they do not care about their future. They delay because the work feels important, interconnected, and easy to postpone while patients and employees need them today.
Structured planning turns that uncertainty into a manageable process. It connects practice performance to personal wealth, replaces vague goals with a financial baseline, and gives the owner a clear next decision.
Econologics Financial Advisors has advised physical therapy practice owners for more than 17 years. Its planning process is designed to align practice and household finances and help owners measure progress toward their personal and professional goals.
Schedule a complimentary consultation to begin building a financial plan around both your practice and the life you want it to support.
Frequently Asked Questions
Why do healthcare practice owners delay financial planning?
Healthcare practice owners often delay because urgent operational demands take priority, income and cash flow can vary, and business and personal decisions are closely connected. Unclear financial data, uncertainty about where to begin, and discomfort with complex decisions can add to the delay.
When should a physical therapy practice owner begin financial planning?
Planning can begin as soon as the practice owner has decisions to coordinate; they do not need to wait until the business reaches a specific revenue level. Starting earlier creates more time to build reserves, evaluate compensation, address debt, fund long-term goals, and prepare for eventual succession or sale.
How is financial planning for a practice owner different from personal financial planning for doctors or other employees?
A practice owner’s income, taxes, benefits, liquidity, and retirement options may all be affected by business performance and structure. Their plan may also need to account for practice value, owner dependence, employees, succession, and the balance between reinvesting in the business and building personal wealth.
Should business and personal finances be kept separate?
Yes. Practice and personal accounts and records should generally be kept distinct for clean accounting and administration. However, the two sides should be considered together when setting compensation, savings, tax, protection, retirement, and exit goals.
Does a PT owner need a formal practice valuation before beginning a financial plan?
Not necessarily. An initial planning estimate or range may be enough to identify major assumptions and gaps. A qualified formal valuation becomes more important when an owner is preparing for a transaction, partnership change, succession, or another event where value must be established more precisely.
What should a PT owner bring to a first financial-planning meeting?
Useful materials may include recent business and personal tax returns, practice financial statements, debt information, retirement and investment account statements, insurance policies, and a list of personal and business goals. An advisor can help identify anything else needed after the initial conversation.
Sources and Further Reading
- APTA Private Practice: Financial Management
- IRS: Estimated Taxes
- IRS: Help With Choosing a Retirement Plan
- U.S. Small Business Administration: Manage Your Business
This material is for general informational purposes only and is not individualized financial, tax, or legal advice. Consult the appropriate qualified professionals regarding your specific circumstances.